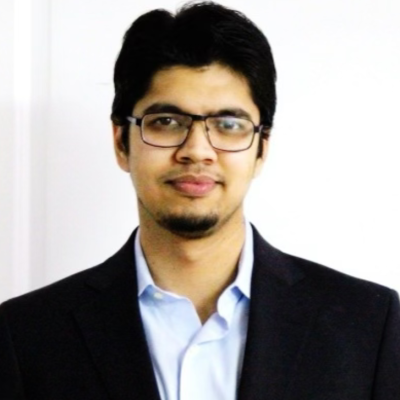
Mayank Saxena is a Quantitative Investment Strategies(QIS) trader at Société Générale with more than 12 years of experience at the intersection of quantitative research, derivatives and systematic investing. His work spans systematic equity and cross-asset strategies, with particular emphasis on volatility, options, portfolio construction, and risk management.
Over his career, Mayank has worked across research, strategy development, structuring, and trading. He brings a practitioner's perspective to how institutional investors can turn quantitative insights into scalable strategies—balancing return objectives with implementation, liquidity, execution, and evolving market risks.
His experience includes equity and index volatility, dispersion, volatility risk premia, tail-risk strategies, commodity volatility, CTA and systematic delta-one strategies. He is an active contributor to the quantitative investing community, sharing insights on the evolution of systematic strategies, volatility investing, and the role of technology and automation in institutional trading.
DAY 2 | Tuesday, January 26
1:45 PM The Future of Systematic Trading — Automation, Autonomy & the 10-Year View
Everyone says "systematic trading." Almost nobody engages with where it's actually going. This session takes the ten-year view: fully automated trading desks, autonomous execution, and the buy-versus-build decision that will define the next decade. With only a handful of firms possessing the data and resources to build what the future requires, what does that mean for everyone else? A candid conversation about the long-term future of the buy-side desk itself.
Check out the incredible speaker line-up to see who will be joining Mayank.
Download The Latest Agenda